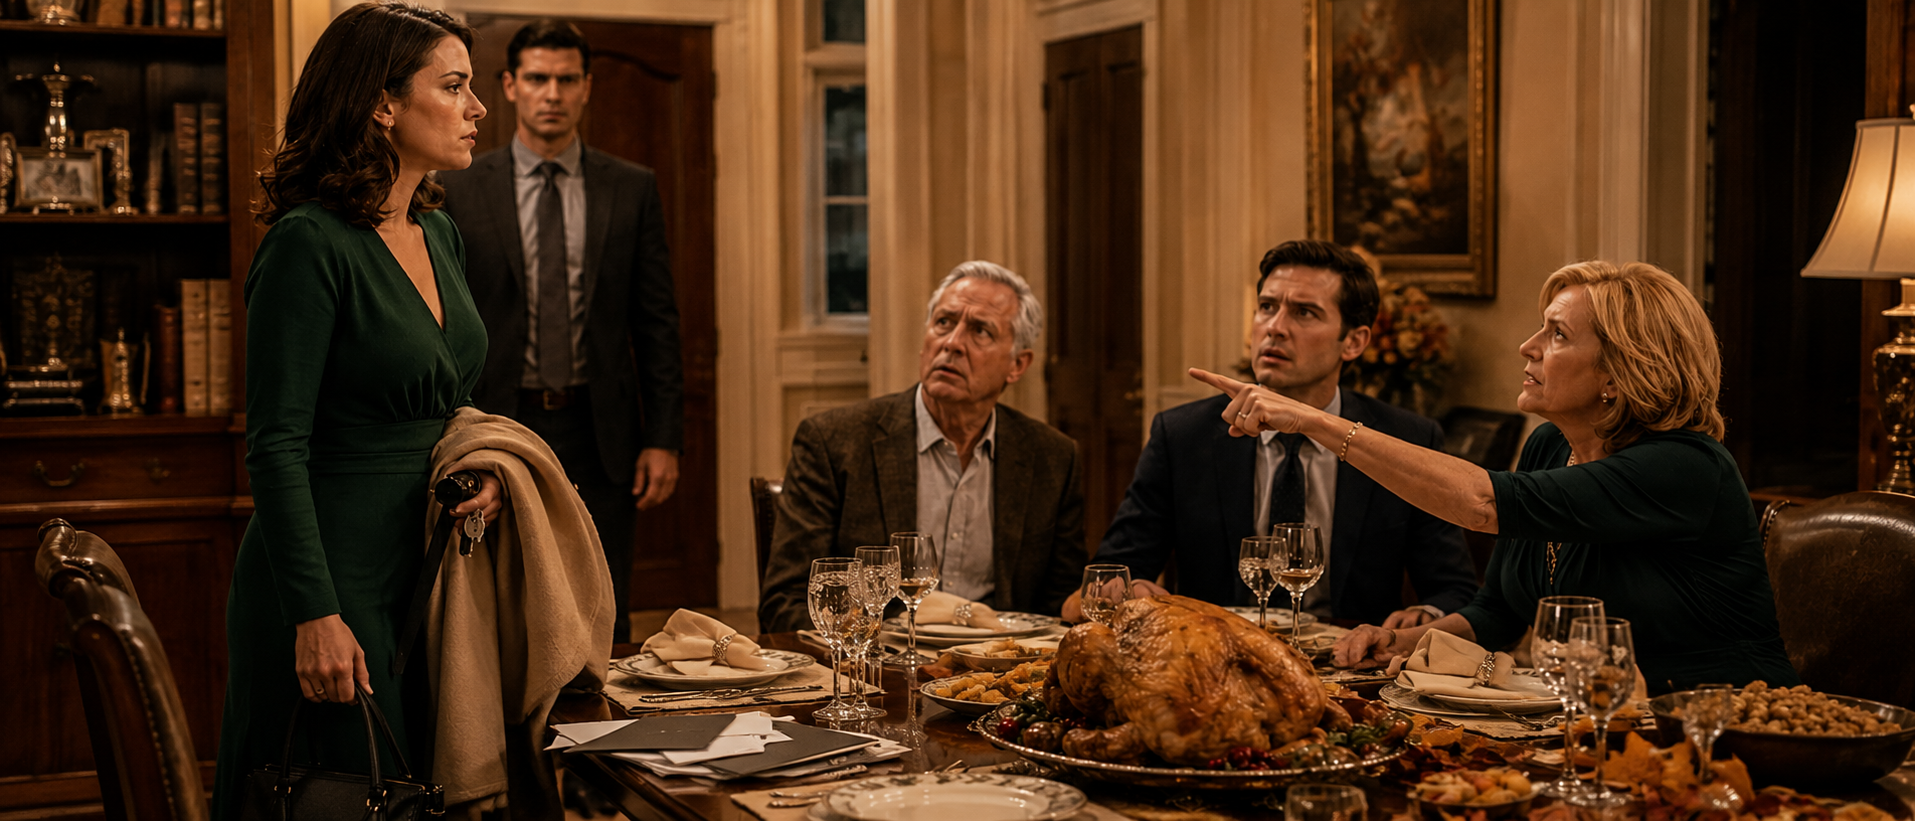
“Your responsibility is to work so your brother can create the future he’s supposed to have.”
My mother said those words calmly during Thanksgiving dinner.
Sitting across from me was my older brother, Carter—thirty-one years old, with six failed businesses behind him, and now asking for $100,000 to launch his latest company, Sello Blue Botanical Co.

I was twenty-nine, working as a portfolio manager in Manhattan, and for the previous five years, I had quietly helped keep my family financially stable.
I covered property taxes, minimum credit-card payments, part of a roof replacement, country-club costs, and debts left behind by Carter’s earlier ventures.
I had always thought I was simply helping my family.
Apparently, they saw it as my duty.
Carter claimed the $100,000 would be an investment.
I asked straightforward questions: Where was the operating plan?
Did he have signed purchase orders? Were there outside investors?
Was the manufacturing contract finalized?
His responses were unclear.
Eventually, Mom lost patience.
“Your brother has ideas.
You have security.
You make good money.
You don’t have children yet.
Carter needs more help.”
Then she made her expectations perfectly clear.
“You’re the one with steady income.
Carter is trying to create something lasting.
Your responsibility is to work so your brother can build the life he deserves.”
I just looked at her.
When I said no, she gestured toward the hallway.
“If helping him is such a problem for you, there’s the door.”
For years, that kind of threat would have frightened me.
Walking away would have meant losing my family’s approval.
This time, I simply got to my feet.
“Fine.”
My fiancé, Marcus, stood up with me.
Before we left, I said, “Beginning tomorrow, you’ll be responsible for your own bills.”
The following morning, I stopped every voluntary payment I had been making for my parents.
Because I had legally guaranteed portions of their mortgage and one of Carter’s business loans, Marcus helped me speak with an attorney.
I couldn’t simply walk away from obligations I had already signed, but I could refuse any new guarantees and decline to renew existing ones.
My family was furious.
Dad reminded me that they had structured their household budget around my financial support.
Mom accused me of being selfish and lacking class.
Carter said I was being spiteful.
I told him, “I want you to succeed without expecting me to take the financial hit if you fail.”
Two weeks later, I uncovered something even more troubling.
Six months earlier, my parents had borrowed $225,000 against their Connecticut home.
Dad admitted that $200,000 of it had gone directly into Carter’s company.
Carter had agreed to make the payments.
He wasn’t making them.
Then I spoke with Carter’s wife, Nia.
She had been told that outside investors were financing the company.
But after reviewing their joint savings account, she discovered that Carter had also transferred $74,000 into the business without telling her.
The situation became painfully clear: Carter’s company wasn’t being sustained by profits or genuine investment.
It was surviving on money taken from the people closest to him.
Not long afterward, a large distributor conducted a review of Sello Blue and discovered that Carter had overstated several aspects of the company.
His supposed purchase orders were mostly nonbinding letters expressing interest, his manufacturing deal offered no exclusivity, and his profit projections were far too optimistic.
The distributor backed out.
Soon after that, my parents received a delinquency notice for their home-equity loan.
Mom showed up at my office and demanded that I cover the overdue payment.
I refused.
“You could save our house with a single transfer,” she said.
“Yes,” I answered.
“But you made the decision to secure this debt with your house.”
Six weeks later, my parents put the property on the market.
The sale brought in enough money to pay off their mortgage, the home-equity loan, taxes, and other outstanding expenses.
Afterward, they moved into a modest condo near Stamford.
Carter’s company shut down around the same time.
There was no explosive scandal or public disaster.
The business simply ran out of money and failed.
Nia separated from Carter, and he eventually agreed to repay my parents over time.
Several months later, Carter asked to meet with me.
“I used to think you were just stingy,” he admitted after finally learning how much money I had contributed to our parents over the years.
Then he apologized.
“For acting like your money already belonged to me.”
I didn’t immediately forgive him, but his apology was a start.
My mother changed as well.
One afternoon, she called me and said, “I never stopped to ask whether being the dependable one was wearing you down.”
Then she apologized for what she had said during Thanksgiving dinner.
Time passed.
My parents learned how to live within their actual budget.
Carter eventually took a regular corporate position and discovered that he was genuinely talented at partnerships and sales—as long as someone else was responsible for payroll, financial planning, and contracts.
Marcus and I got married.
My career continued to grow.
Five years after that Thanksgiving confrontation, we all gathered at my parents’ smaller condo for dinner.
At one point, Carter lifted his glass.
“To Sloan—for being the first person in this family brave enough to stop confusing rescue with love.”
Mom looked directly at me.
“You were right to walk through that door.”
That Thanksgiving hadn’t destroyed our family.
It had forced all of us to change.
My parents learned to survive on what they truly had instead of what they expected me to provide.
Carter learned that ambition and talent don’t excuse anyone from basic financial reality.
And I learned that generosity can slowly turn into obligation when one person is never allowed to say no.
For years, I had mistaken keeping my family financially comfortable for keeping my family united.
Stopping the money didn’t tear us apart.
It made everyone learn how to support themselves.
Eventually, they did.
And so did I—finally building a life on ground I had chosen for myself.